Palm oil prices fall 5% in Malaysia and 6.5% in Rotterdam
Palm oil prices declined during September as Malaysian production and inventories increased while demand weakened in several major importing markets. Future supply remains uncertain because of below-normal rainfall, while Indonesia’s B50 biodiesel program is supporting domestic consumption.
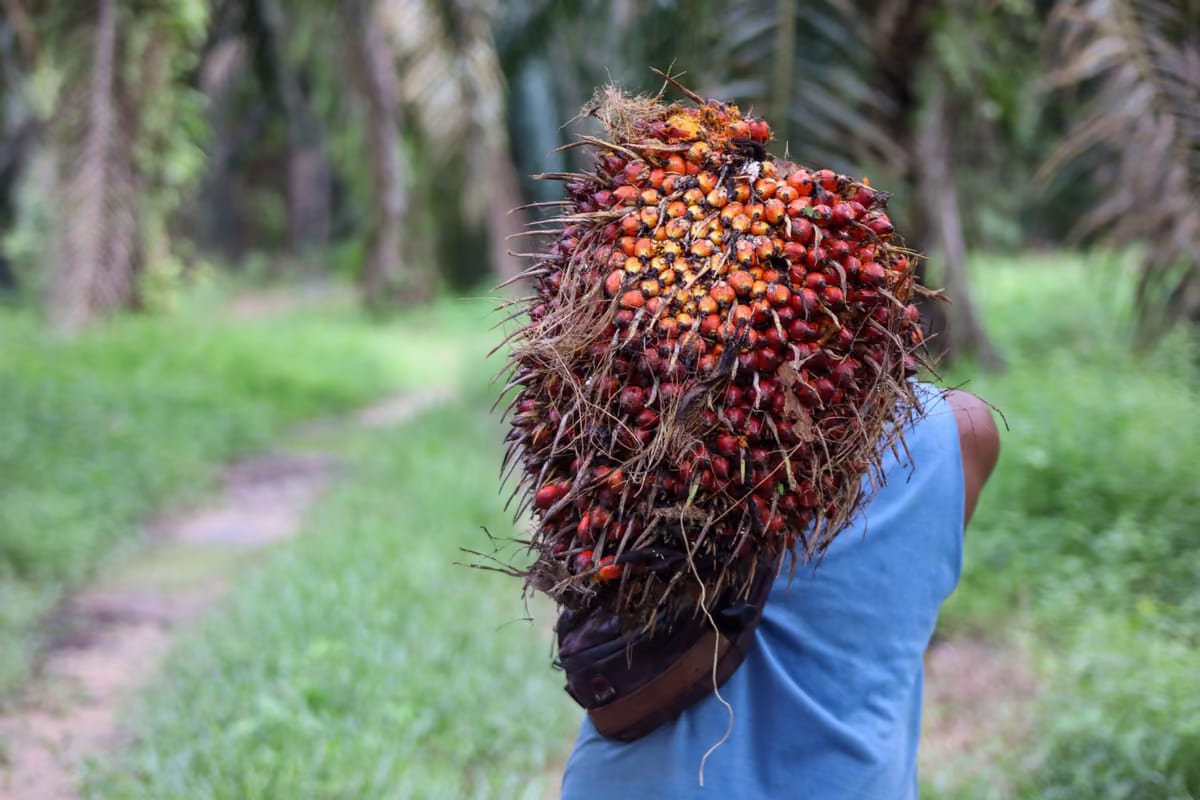
Rising Malaysian stocks weigh on prices
Palm oil prices retreated across two of the sector’s main international benchmarks during September. Between the first and the final day of the month, quotations fell by 5% on Bursa Malaysia and by 6.5% in Rotterdam, according to data from Areté — The Agri-Food Intelligence Company reported by Italia a Tavola. The declines reflected a combination of expanding Malaysian supplies and weaker signals from several major importing markets.
Malaysia’s palm oil inventories increased by 7% in August compared with July and stood 28% above their level a year earlier. Production also continued its seasonal recovery, rising by another 1% from the previous month. The simultaneous increase in output and stocks gave buyers more available supply and reduced immediate pressure on prices. For producers and traders, the figures indicate that current Malaysian availability is growing faster than demand can absorb it.
China and the EU provide weaker demand signals
China sharply reduced its palm oil purchases in August. Imports were 42% lower than in July and 43% below the same month of the previous year. The short-term contraction does not, however, describe the entire annual trend: Chinese imports since the beginning of the year remained 9% higher. This divergence suggests that accumulated purchases were still strong, even as the country’s immediate buying appetite weakened.
Demand in the European Union also remained below recent levels. According to Areté, EU imports during the 2025/26 season were 6% lower than in the preceding season and 22% below the average of the previous three seasons. India, another major vegetable-oil market, continued to hold elevated inventories. Together, slower Chinese purchases, subdued European imports and ample Indian stocks limited the need for importers to compete aggressively for additional cargoes.
Biodiesel demand meets climate uncertainty
Indonesia is providing a counterweight to the weaker international demand picture through its B50 program, which raises biodiesel’s share in diesel blends to 50%. Implementation of the mandate supports domestic palm oil consumption and can reduce the volume available to the international market. A possible move to B60, increasing the biodiesel component to 60%, is under consideration for 2027. The scale and timing of that policy will matter to exporters, refiners and buyers assessing future Indonesian availability.
Supply risks have not disappeared despite the current buildup of Malaysian inventories. Rainfall remains below normal in the main producing areas, and market attention is focused on whether El Niño could reduce precipitation in Southeast Asia and affect productivity in 2027. Buyers therefore face a market in which near-term fundamentals are softer, but future production is less certain. The September correction offers processors and importers lower benchmark prices, while the combination of Indonesian biodiesel demand and weather risks could limit how long the present supply pressure persists.