RHB sees palm oil prices rising in early 2026 as inventories retreat from record highs
RHB Research expects crude palm oil prices to recover in the first half of 2026 as inventories decline from current peaks. The firm maintained forecasts of 4,400 ringgit per tonne for 2026 and 4,500 ringgit for 2027, while Indonesian biodiesel policy and Indian import demand remain key variables.
Record output keeps the market in a holding pattern
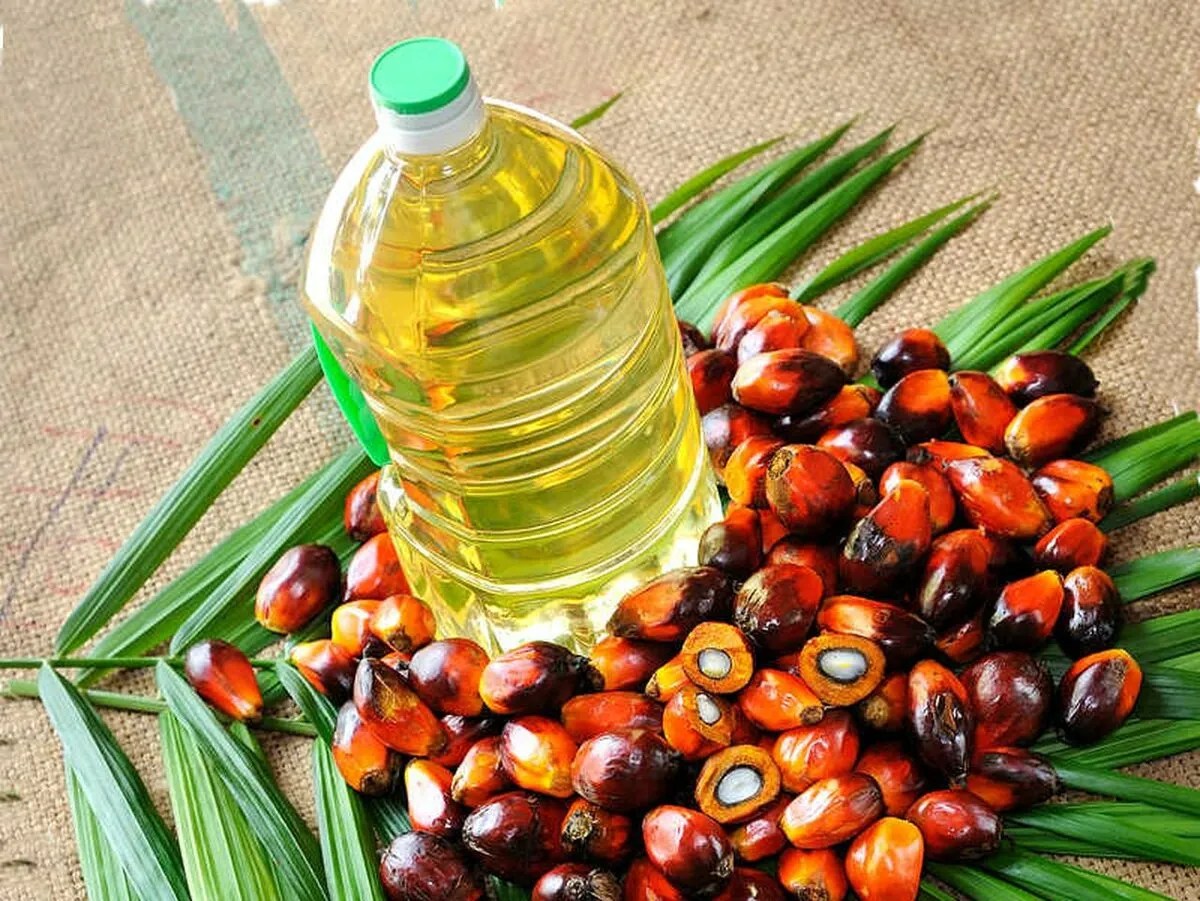
Crude palm oil prices could begin rising in the first half of 2026 as inventories retreat from their current peaks, according to RHB Research. In the near term, however, record production and full storage facilities are expected to keep prices trading within a relatively narrow range, OleoScope reported, citing Prestasi Sawit Malaysia.
RHB maintained its medium-term crude palm oil forecast at 4,400 ringgit per tonne for 2026 and 4,500 ringgit per tonne for 2027. The outlook implies that the immediate burden of abundant supply may ease, but the anticipated recovery depends on inventories normalizing and demand absorbing the available volumes. For producers, the forecast offers the prospect of firmer revenue after the current period of supply pressure. Importers and processors may face higher feedstock costs once stocks begin to decline.
Oil rally has delivered a limited lift to palm oil
Spot crude palm oil prices have been volatile amid tensions in the Middle East, although their relationship with crude oil has weakened. RHB said the correlation coefficient fell from a peak of 0.91 in the second quarter to 0.59. Over the reporting period, crude oil gained 38.6%, compared with a 17% rise in palm oil. The difference suggests that geopolitical pressure in energy markets has not been transmitted fully to vegetable oil prices.
Palm oil was consequently trading at a discount of $19 per barrel to gasoil, pushing the palm oil-gasoil, or POGO, spread into negative territory. This improves palm oil's relative attractiveness as a biodiesel feedstock, but policy decisions remain critical to actual consumption. RHB said that if the POGO spread returns to positive territory, Indonesia could be encouraged to raise its biodiesel blending mandate from 50% to 60% by 2027. Such a move could remove another 5–6 million tonnes of palm oil from the global market and restore up to 3 million tonnes of discretionary biodiesel demand annually.
Indonesia and India could reshape the balance
Indian demand is expected to recover from the end of September following New Delhi's decision to halve the import duty on crude palm oil from 10% to 5%. The tax on refined palm oil was also reduced, from 32.5% to 27.5%. The wider duty gap between crude and refined products supports purchases of crude oil by Indian refiners and could accelerate the drawdown of inventories elsewhere in the supply chain.
Supply uncertainty is also increasing in Indonesia, where a proposed agrarian reform law could require plantation owners to transfer 20% of their land or pay special levies. RHB said it remains unclear whether existing arrangements could satisfy the requirement and whether current owners would be affected despite assurances that the measure would not apply retroactively. If enacted in a form that disrupts established plantations, the legislation could reduce Indonesian productivity and further restrict global supply. The price outlook therefore rests on three linked developments: the pace of inventory normalization, the scale of Indonesian biodiesel consumption and land-policy changes, and the strength of India's renewed import demand.