Poland records EU’s steepest sugar price decline as beet campaign begins
Polish retail sugar prices fell 16.6% year on year in July 2026, the sharpest decline in the EU. The new beet campaign is expected to produce 2.0–2.1 million tonnes of sugar, leaving Poland dependent on exports to absorb output above domestic consumption.
Poland posts the EU’s largest price decline
Poland entered its 2026/27 sugar beet-processing campaign with domestic sugar prices substantially below the previous year’s levels. Processing began at the end of August, with additional factories and the first beet harvests following in subsequent days. The weak price environment raises the pressure on growers and refiners as new production reaches a market that is already well supplied.
According to Piotr Szajner of the Institute of Agricultural and Food Economics — National Research Institute in Warsaw, the ex-works price of bagged sugar fell 2.0% from June to PLN 2.46 per kilogram in July 2026. That was 15.5% below July 2025. The average retail price declined 1.1% month on month to PLN 2.75 per kilogram and was 15.6% lower than a year earlier.
Price movements diverge across Europe
The Institute’s report showed that Polish retail sugar prices recorded the steepest year-on-year fall in the EU, dropping 16.6%. Slovenia followed with a 16.0% decline, while Denmark registered a 12.8% decrease. Prices fell 7.8% in France and 3.1% in the Netherlands, but rose 4.6% in Germany and 4.3% in Austria.
High availability across the European market is weighing on prices. European Commission estimates cited by farmer.pl put EU sugar production in the 2025/26 season at 16.6 million tonnes, up 0.2%. Imports increased 5.2% to 1.5 million tonnes, while internal consumption grew 1.4% to 13.8 million tonnes. EU exports fell 5.2% to 4.0 million tonnes, leaving more supply to compete within the bloc.
Exports remain essential for Poland
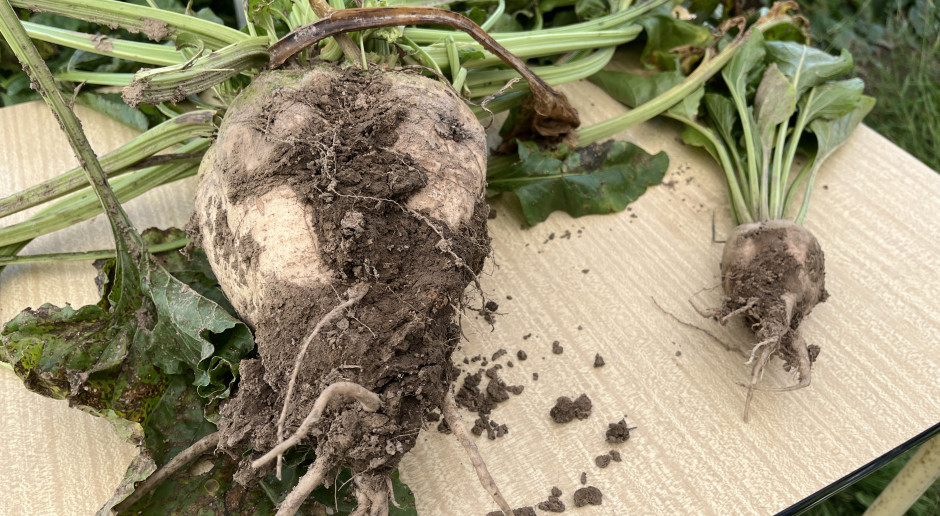
Poland’s new crop is expected to yield an average of 65–67 tonnes of sugar beet per hectare. The technological sugar yield is provisionally estimated at 8.5–9.0 tonnes per hectare. Sugar production is forecast at 2.0–2.1 million tonnes, below the approximately 2.5 million tonnes produced in each of the previous two campaigns but still above national consumption of 1.8 million tonnes.
This surplus makes foreign demand a central part of the Polish market balance. In the first half of 2026, Poland exported 512,900 tonnes of sugar, including 200,000 tonnes to other EU countries, according to the Institute’s report. The average transaction price was EUR 456 per tonne across all destinations and EUR 548 per tonne within the EU. Germany was the largest EU buyer at 60,500 tonnes, followed by Hungary at 22,800 tonnes, Lithuania at 18,300 tonnes and Romania at 14,400 tonnes.
Global surplus limits prospects for recovery
International prices also remained low, although they strengthened in August. USDA figures cited by Szajner placed July white sugar at USD 464 per tonne and raw sugar at USD 326 per tonne. International Sugar Organization data showed August prices rising to USD 506 per tonne for white sugar and USD 350 per tonne for raw sugar. Szajner said the increase may be linked to the armed conflict in the Persian Gulf, which has reduced supply and raised crude oil and liquefied natural gas prices.
Energy markets matter because Brazil can divert large volumes of sugar cane into ethanol for liquid fuels. Even so, global supply remains the dominant pressure. USDA Economic Research Service estimates put 2026/27 world sugar production at 184.9 million tonnes, down 0.6%, against stable consumption of 180.5 million tonnes. Ending stocks are forecast to rise 2.0% to 44.4 million tonnes. For Polish producers and refiners, the combination of domestic surplus, weaker EU exports and rising global inventories limits the scope for a rapid price recovery.