Chile reviews Asia strategy as table grape exports to China fall 40%
Chile's table grape committee says expanding local production in China and South Korea has cut the space for imported fruit, with Chilean shipments to China down 40% last season. China is now the world's largest table grape exporter at close to 800,000 tonnes, while the United States still absorbs 52% of Chilean grape exports.
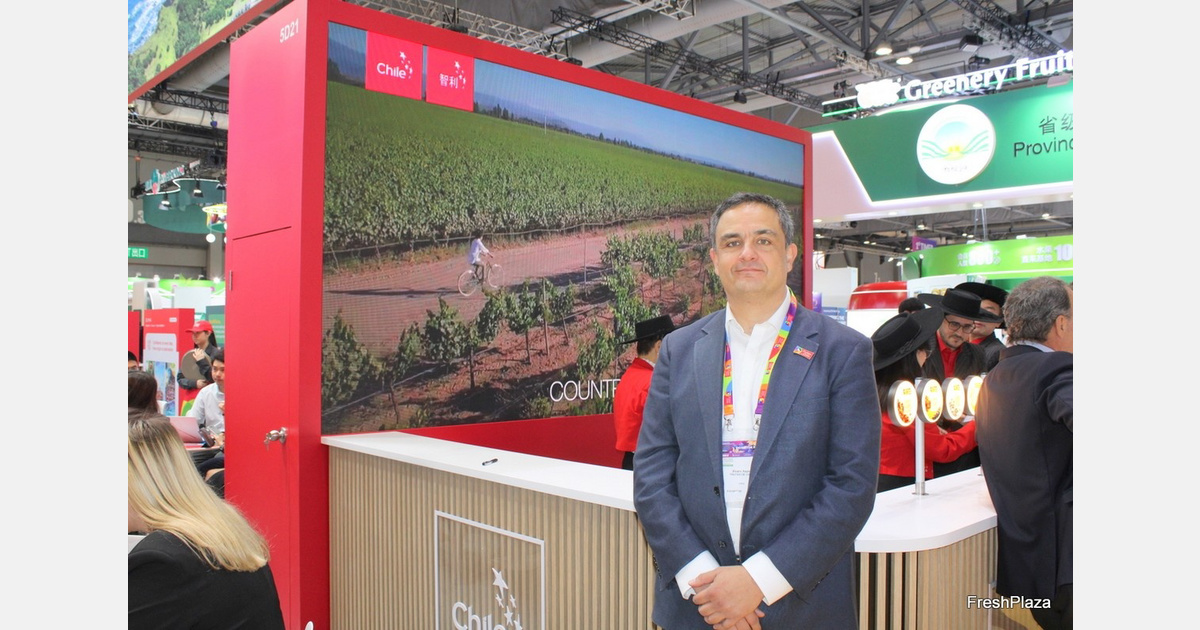
Chile's table grape sector is reassessing its approach to Asia after a sharp drop in shipments to China, where expanding domestic production has reduced the space available for imported fruit. Álvaro Aspee, executive director of the Comité de Uvas de Frutas de Chile, set out the industry's position during Asia Fruit Logistica, in remarks reported by FreshPlaza.
“Asia for us is a big market for all fruit, and in the case of grapes it is very important,” Aspee said, while acknowledging that the region “faces a reality, which is local production, that has been transforming through new varieties and new technologies.” He pointed to China and South Korea as the markets where domestic supply has advanced most visibly.
China has become the world's largest table grape exporter
According to Aspee, China is now the world's largest exporter of table grapes, with close to 800,000 tonnes traded, displacing in part origins such as Chile, Peru and Australia. The shift has fed directly into South American volumes: Chilean exports to China “fell 40%” last season, he said, describing a trend that becomes more pronounced when measured over the past five years.
India is currently the main destination for Chinese grape exports. Aspee argued that the development of the category in large Asian markets such as China and India could eventually work in favour of every origin, by widening consumption and making Asian consumers familiar with grapes throughout the year rather than in a single seasonal window.
Planted area inside China is also shifting. Aspee said growers are pulling out orchards of varieties that have not performed well in particular zones, an adjustment process he described as still unresolved. In the meantime, the committee is tracking emerging markets within the region, including Vietnam, where exports have shown growth.
The 2026-2027 season is still unquantified
Aspee said it is too early to project volumes for the 2026-2027 season, although a recovery is expected after the 14% decline recorded last season as a result of rain in March. The Comité de Uvas is working with exporters on an estimate to be presented at Fruit Attraction in Madrid in October, or at a comparable European event, and updated as the season progresses.
No volume figure was given for the coming crop, and the committee did not quantify how much of the lost Chinese demand has been redirected to other destinations.
Sizing standards and joint category promotion
In parallel, Chile is advancing a voluntary harmonisation of size grades among exporters, an effort aimed at unifying the industry's commercial language.
- “When a single language is used, statistics are easier, purchasing is easier, and it gives fluidity to the whole mechanism,” Aspee said.
- The committee is also working with Peru and Mexico through the Global Grape Group, which aims to lift demand for grapes as a category worldwide.
- The United States remains the leading destination for Chilean grapes, taking 52% of exports.
Diversification remains the stated goal
Despite that concentration in North America, the committee continues to stress the importance of maintaining market diversification that is sustainable over time. The combination of a dominant United States share and a contracting Chinese outlet frames the commercial question the sector is now working on: how to replace Asian volume without deepening dependence on a single destination.
The long-term reading offered at Asia Fruit Logistica is that consumption growth in Asia, rather than access alone, will determine how much room remains for imported fruit. That view rests on Asian buyers treating grapes as a year-round category, a shift that would give counter-seasonal suppliers such as Chile a structural reason to stay in the region even as local output expands.