Vietnam's Beer Sector: Revenue Up 7% in H1 2026 as Profit Jumps 29%
Fifteen Vietnamese beer companies that have published half-year accounts reported combined revenue of more than 24 trillion dong in the first half of 2026, up 7% year on year, with after-tax profit rising 29% to more than 3 trillion dong. Thương Trường reports the recovery is uneven, with the largest producers accounting for the bulk of the profit.
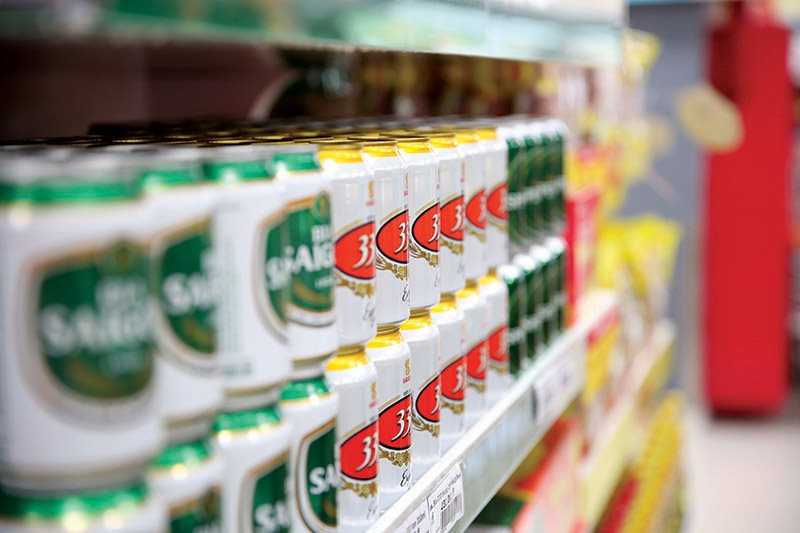
Vietnam's brewing industry returned to growth in the first half of 2026, but the gains were spread unevenly across the sector. Fifteen beer companies that have published financial statements for the period reported combined revenue of more than 24 trillion dong, up 7% year on year, while combined after-tax profit rose 29% to more than 3 trillion dong, according to Thương Trường.
The tally covers only those producers that had disclosed half-year results at the time of the report. It is a broad but incomplete read on a market that also contains privately held and foreign-controlled operations which do not publish interim accounts.
Profit growing four times faster than revenue
The defining feature of the half-year is the gap between the two headline rates: profit grew more than four times as fast as revenue. Calculated from the reported aggregates, the group's net margin works out at roughly 12.5% for the first six months of 2026, against about 10% implied for the same period a year earlier. On those numbers the recovery is being driven by margin, not by volume alone — a market rebounding purely on higher sales would show profit and revenue moving at closer to the same pace.
Margin improvement of that size usually reflects some mix of firmer pricing, a richer product mix, cheaper inputs and packaging, and cost discipline retained from the downturn. The published summary does not attribute the improvement to any single driver, and separating price effects from cost effects would require the individual company statements.
The largest brewers take most of the upside
Thương Trường characterises the recovery as uneven, with the biggest companies accounting for the bulk of the sector's profit. Aggregate figures of this kind conceal that split: a 7% revenue increase across 15 companies is consistent with strong growth at a handful of leaders and flat or declining business elsewhere, and a 29% profit jump is easier to generate at scale than at the bottom of the table.
The distinction matters in practice for several groups:
- Suppliers of malt, hops, packaging and logistics services, whose order books concentrate further when a small number of buyers capture most of the growth.
- Distributors and retailers, for whom shelf space and trade terms follow the brands with marketing budgets large enough to defend volume.
- Investors and lenders assessing smaller regional brewers, whose results may not resemble the sector average in either direction.
What to watch next
Beer is one of Vietnam's larger packaged-goods categories by value, and the industry is a substantial buyer of imported inputs: malting barley and malt, hops and aluminium for cans are not available domestically at the scale local brewers require. A 7% rise in sector revenue therefore translates into procurement demand, but concentration determines which companies place those orders and on what terms.
For the rest of 2026, the question is whether margin expansion of this scale is repeatable once the easiest cost comparisons are behind the industry. If revenue growth stays in the mid-single digits while profit growth normalises, the 29% figure will read as a one-off catch-up from a weak base rather than a new earnings level. The individual filings of the 15 reporting companies — and the results of producers still to disclose — will determine how much of the recovery is genuinely sector-wide.