Polish raspberry prices rise as tighter supply meets growing imports
Polish freezing-grade raspberry prices reached 18.50–19.50 zł/kg for extra-class fruit around the turn of September and October. Higher purchasing costs are supporting growers but pressuring processors as imports from Ukraine and Morocco expand.
Processing prices climb through the season
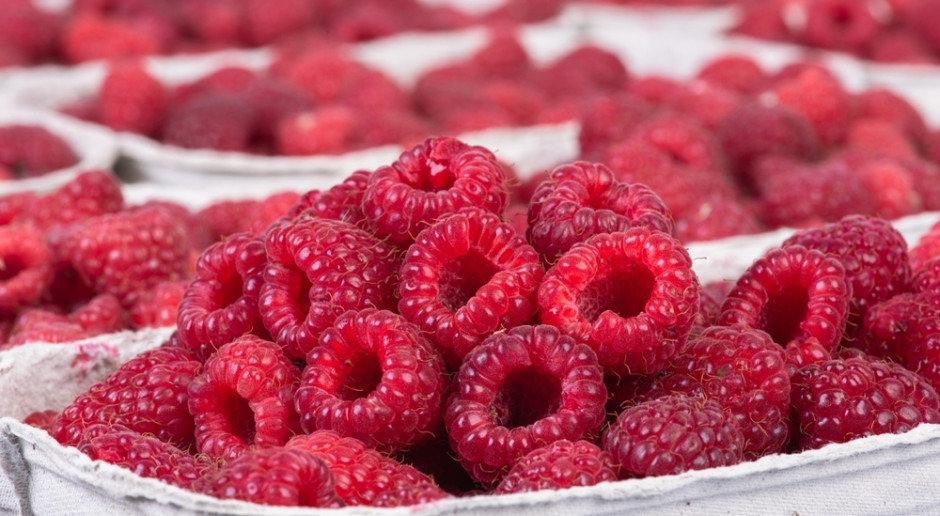
Polish raspberry prices increased steadily during the season despite brief reversals between the summer and autumn harvests, according to Portal Spożywczy. At the start of the season, raspberries intended for pressing were purchased for about 9 zł/kg, while freezing-grade fruit commanded slightly higher prices. By the end of the summer-variety harvest, purchasing prices had risen to 15–16 zł/kg, with premiums available for the highest-quality fruit.
Around the turn of September and October, extra-class raspberries for freezing reached 18.50–19.50 zł/kg. First-class fruit traded at 18–19 zł/kg, while second-class berries fetched 17–18 zł/kg. The highest offers were recorded in the main production area of Lublin, reflecting competition for suitable raw material as the harvest approached its end.
The increase benefits growers after several years of volatile prices, supply and demand. For freezing plants and other processors, however, the same movement raises raw-material costs and increases exposure to changes in finished-product prices. Companies focused narrowly on raspberry processing have been particularly vulnerable, while diversified operators have had more options to absorb market swings.
Processor stress predates the import increase
The pressure on processors became visible when the management of one company began a hunger strike during the summer and sought state assistance. Its representatives said an influx of inexpensive Ukrainian raspberries was one cause of the company’s financial difficulties. The ministry declined to provide a loan, citing insufficient liquidity and a high risk that public funds would not be recovered.
Government institutions said the company’s problems had begun before imports from Ukraine increased. According to their assessment, the business had already been recording losses and financing a substantial share of its operations through credit and loans. The case nevertheless illustrates the broader pressure on cold stores and processing businesses operating in a market marked by large shifts in purchase prices and product availability.
Imports reach 44,000 tonnes
Preliminary Ministry of Finance data cited by Portal Spożywczy show that Poland imported 44,000 tonnes of raspberries in the 2025/26 season, an increase of 24% from the previous season. Average annual imports in the 2021/22–2023/24 seasons were just under 31,000 tonnes, indicating that foreign fruit has taken a larger role in supplying Polish processing and trading operations.
Ukraine was the largest supplier. Poland imported 28,000 tonnes of frozen raspberries from Ukraine in 2025/26, 27% more than a year earlier. Ukrainian fruit represented 63% of total imports in this category. Deliveries from Morocco also increased, rising from about 2,000 tonnes to 5,000 tonnes.
Poland nevertheless remained a net exporter of raspberries, with foreign sales estimated at 52,000 tonnes in 2025/26. This combination of sizeable imports and larger exports reflects Poland’s position as both a production base and a processing and distribution hub for the European market.
Ukraine and Serbia shape regional competition
Poland is the leading destination for Ukrainian frozen raspberries. Estimates from the Ukrainian berry association indicate that it accounted for about 40% of the value of Ukraine’s exports of the product in 2025. Germany and the Czech Republic were the next important destinations. More than 90% of raspberries harvested in Ukraine are frozen and exported, while industry forecasts put exports in recent seasons at 55,000–65,000 tonnes.
Serbia is another major competitor. Its raspberry harvest was preliminarily estimated to have grown by 15% from 2025, although that comparison follows a year of record-low production. The additional supply reduced Serbian selling prices, but they remained above levels seen in high-yield years. For Polish market participants, relatively limited Serbian supply has supported purchasing prices, while the expanding presence of Ukrainian frozen fruit continues to intensify competition for processors, traders and exporters.