Natural rubber supply tightens as weather hits Asian output and prices rise
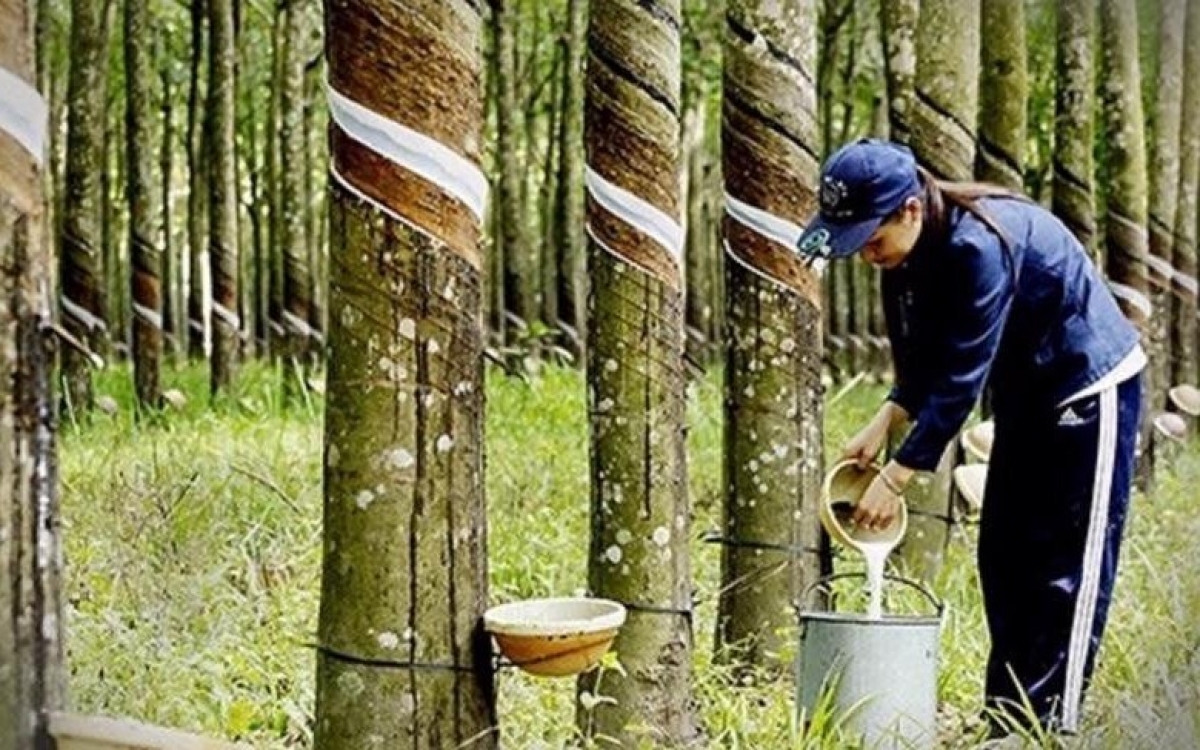
Natural rubber production is struggling to keep pace with consumption as adverse weather disrupts Asian supply. Export declines in Thailand, Vietnam and Indonesia have helped lift benchmark prices, although weaker consumption growth and trade risks cloud the outlook.
Global market heads for a narrow deficit
Global natural rubber supply is set to remain tight in 2026 as adverse weather, weak replanting and geopolitical disruption constrain production. The Association of Natural Rubber Producing Countries, cited by VietnamBiz, forecasts output of 15.279 million tonnes, up 2.1% from 14.971 million tonnes in 2025. Consumption is expected to rise only 0.4% to 15.356 million tonnes, leaving projected demand 77,000 tonnes above production.
The consumption forecast was reduced from ANRPC’s June estimate after weaker expectations for Japan, South Korea, Mexico and other markets. Replacement-tyre demand, expanding electric-vehicle markets in China, India and Europe, and continued automotive manufacturing growth still support consumption. However, seasonal weakness in tyre production, higher raw-material costs, trade restrictions and geopolitical disruption are limiting growth.
Weather remains the main supply risk. Uneven rainfall, high temperatures and the emerging El Niño phenomenon have slowed the recovery of tapping volumes. ANRPC estimated July production at 1.321 million tonnes, down 5.15% year on year, while consumption reached 1.297 million tonnes, up 0.8%.
Asian production and exports come under pressure
Thailand is forecast to remain the largest producer in 2026 with 4.867 million tonnes, up 1.4%. Indonesia’s output is expected to fall 0.8% to 2.025 million tonnes, while Vietnam’s is projected to decline 4.2% to 1.290 million tonnes. India and China are expected to increase production by 4.4% and 2.9%, respectively, to 943,000 tonnes and 955,000 tonnes.
According to Vietnam Financial Times, combined exports from Thailand, Vietnam and Indonesia fell nearly 15% year on year in the first seven months of 2026 to 2.98 million tonnes. Vietnam exported an estimated 936,100 tonnes worth $1.86 billion in the first eight months, down 16.1% by volume and 6.2% by value. The average export price nevertheless rose 11.9% to $1,986 per tonne.
China accounted for 58.4% of Vietnam’s rubber exports, followed by India with 8.2% and Indonesia with 7.4%. Export value to China declined 20.3%, while shipments by value to India increased 49.7% and those to Indonesia rose 2.6 times. The concentration leaves Vietnamese suppliers exposed to changes in Chinese demand and trade policy.
Malaysia illustrates the supply and price volatility
Malaysia produced 26,817 tonnes in July, 1% more than in June but 25.3% less than a year earlier, according to the Department of Statistics Malaysia. Stocks fell 0.7% month on month to 128,946 tonnes. Natural rubber exports rose 6.2% to 41,241 tonnes, with China taking 45.2%, Germany 14.4% and the United States 9.1%.
Prices weakened in Malaysia during July, but international benchmarks subsequently advanced. Vietnam Financial Times reported that RSS3 futures rose above $3,100 per tonne on September 10, their highest level in five years and seven months, while TSR20 reached $2,468 per tonne, its highest in nearly 13 years. Cost pressure is therefore building for tyre manufacturers, while producers and traders face continued volatility from weather, oil prices and geopolitics. Vietnamese exporters must also invest in traceability as the European Union prepares to implement its deforestation regulation during 2026-2027.