Malaysia still imports about 26 million litres of fresh milk a year as self-sufficiency holds near 62%
Malaysia needs to import roughly 26 million litres of fresh milk annually because its self-sufficiency level for the product stands at about 62 percent, Bernama reported from Kuala Terengganu. The two figures imply national fresh-milk demand of around 68 million litres a year, with local farms covering about 42 million. The shortfall is structural and, in a perishable category, must be met by continuous chilled supply rather than spot purchases.
A 26-million-litre gap in fresh milk
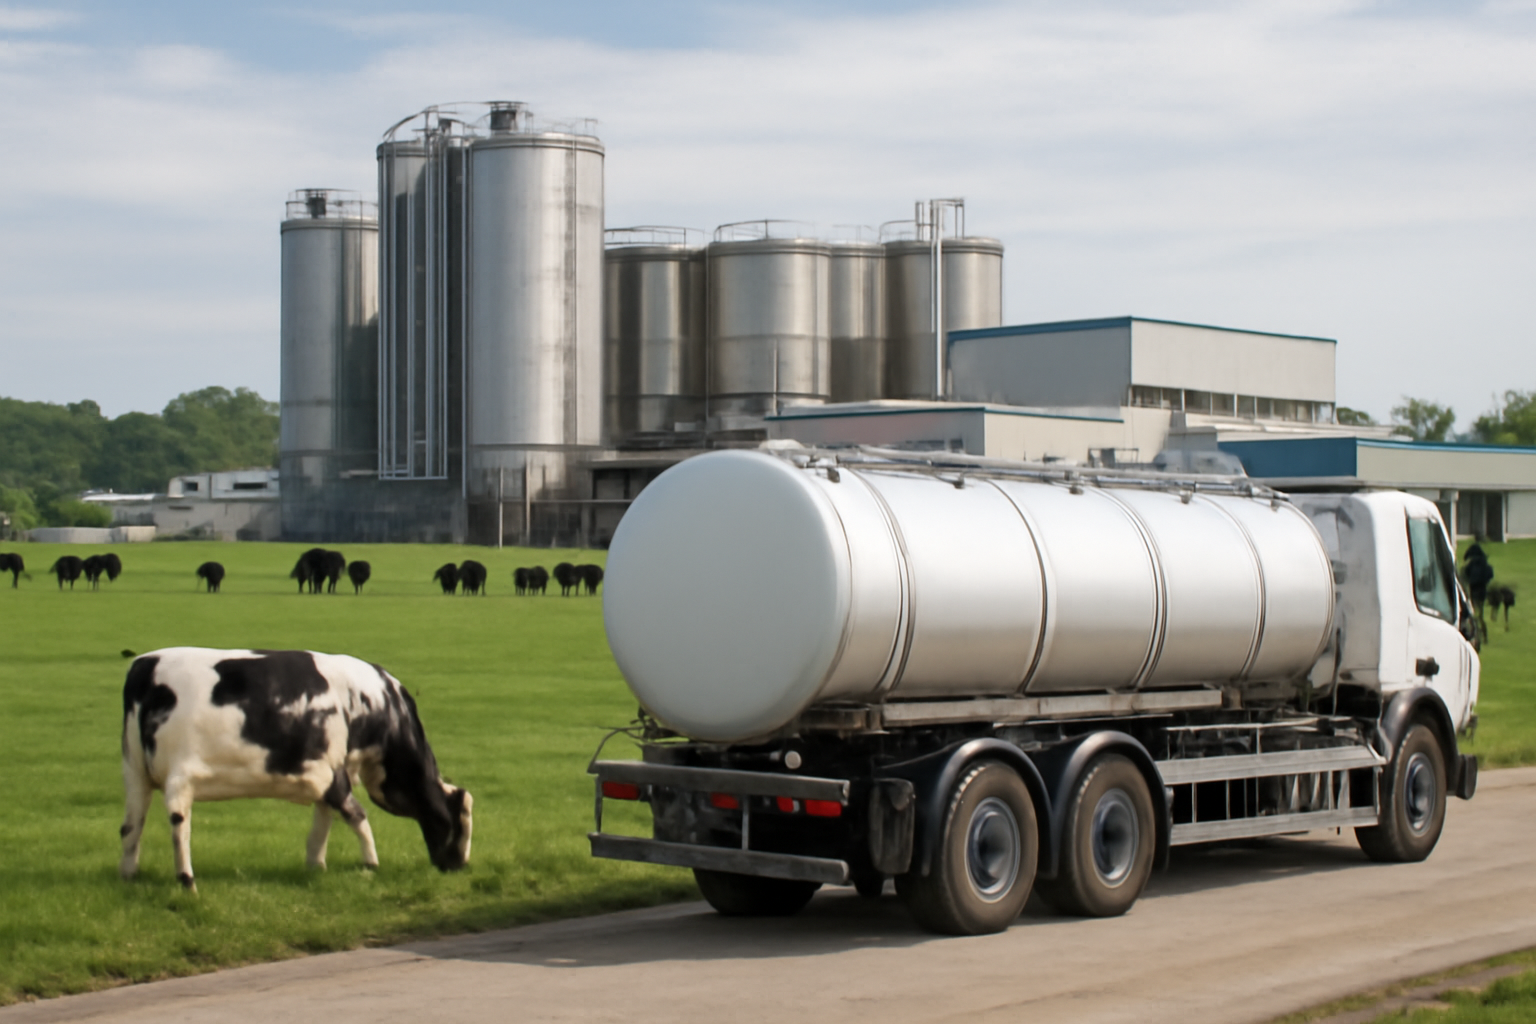
Malaysia still needs to import about 26 million litres of fresh milk a year to meet national demand, with the country's self-sufficiency level for the product at around 62 percent, Bernama reported from Kuala Terengganu on 22 September, citing an expert. The news agency did not report a target date for closing the gap.
The two figures frame the size of the market. If the 26 million litres represent the portion of fresh-milk demand not covered by local farms, total national demand works out to roughly 68 million litres a year, of which domestic production supplies about 42 million. Those totals are arithmetic implications of the figures carried by Bernama rather than separately reported numbers, but they set the scale of the addressable volume for local producers and foreign suppliers alike. In absolute terms the market is modest, which limits the economies of scale available to domestic processors.
Reading a 62 percent self-sufficiency rate
Self-sufficiency ratios in dairy are sensitive to the category being measured. Fresh milk is a narrower segment than dairy as a whole: a market can cover most of its liquid-milk needs domestically while importing nearly all of its milk powder, butter and cheese, or the reverse. The figure cited by Bernama refers to fresh milk specifically and should not be read as a measure of Malaysia's overall dairy import dependence.
The ratio is also a moving target. Holding it at 62 percent requires domestic output to expand at the same pace as consumption; lifting it requires output to grow faster than demand. In practical terms that means more animals in milk, higher yield per animal, or both, and none of that can be delivered within a single season.
What the shortfall means for processors and importers
For companies on both sides of the trade, a standing 38 percent shortfall in a perishable category has specific consequences:
- Fresh milk cannot be warehoused like powder, so the imported volume has to arrive on a continuous schedule rather than in opportunistic spot lots.
- Every imported litre carries freight, cold-chain and currency exposure on top of the farmgate price, which transmits external cost shocks directly to domestic retail shelves.
- A recurring annual requirement of this size favours contracted supply relationships over transactional buying and rewards suppliers able to guarantee consistent chilled delivery.
What would move the number
Closing a gap of this kind is a capacity question rather than a trade-policy one. Herd expansion, yield improvement, feed availability and cold-chain coverage all have to move together, and each is capital-intensive. Producer pricing and investment in chilled logistics are the usual levers, but the report did not detail any new programme. Until domestic capacity moves, the imported share remains the balancing item between local supply and consumption.
Bernama's report does not indicate whether the 62 percent rate has been rising or falling, nor does it give a volume target for domestic output. For analysts tracking the sector, those two data points, the direction of the self-sufficiency rate and the trajectory of national fresh-milk consumption, determine whether the 26-million-litre import requirement grows or shrinks in the years ahead.