FAO: Higher Kazakh Wheat Exports Fall Short of Covering Lower Russian and Ukrainian Shipments
The FAO has raised its wheat export expectations for Kazakhstan while cutting projected shipments from the Russian Federation and Ukraine, according to apk-news.kz. The net effect on the regional export pool is negative, and Kazakh grain cannot substitute one-for-one for Black Sea cargoes because it moves by rail rather than deepwater port.
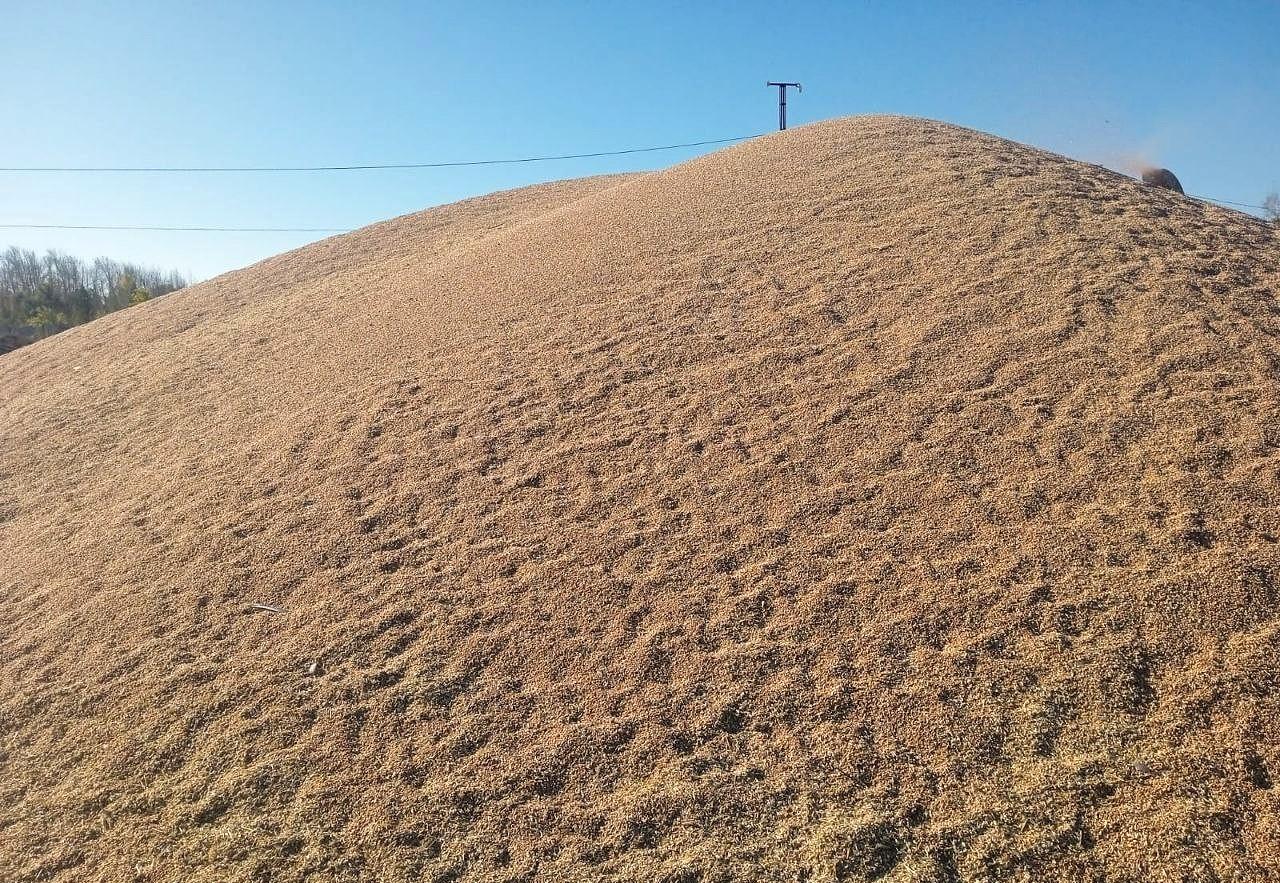
Kazakhstan is set to ship more wheat to the world market, but the increase will be more than cancelled out by lower expected supplies from the Russian Federation and Ukraine, according to the latest outlook from the Food and Agriculture Organization of the United Nations (FAO), as reported by apk-news.kz.
One exporter up, two down
The FAO outlook moves in two directions at once. Export expectations for Kazakhstan have been revised higher, while projected shipments from Russia and Ukraine have been revised lower. The organisation is explicit that the stronger Kazakh outlook is more than offset by the reductions for its two Black Sea neighbours, so the net change to the regional export pool is negative rather than neutral.
That distinction matters for anyone balancing a wheat book. A single-country upgrade does not restore the aggregate. Russia and Ukraine together have anchored the low-cost end of the world wheat market for several seasons, setting the reference level that buyers in North Africa, the Middle East and Asia build their purchasing around. When projected availability from those origins falls, importers either pay more or shift to origins that arrive later and cost more to move.
Kazakh wheat is not a drop-in substitute
The additional Kazakh tonnage will not simply slot into the space left by Russian and Ukrainian sellers. Kazakhstan is landlocked, and its grain reaches customers by rail and road rather than from deepwater ports. That shapes both who can buy it and at what delivered cost. Its traditional customer base sits in Central Asia and neighbouring markets, where rail freight is competitive; serving buyers that normally load Black Sea bulk vessels requires transit through third countries and adds handling steps.
Product mix also differs. Kazakhstan is a significant supplier of milling wheat and of wheat flour, and its flour trade competes with milling capacity inside importing countries rather than with bulk grain cargoes. Any reallocation of volume between flour and unmilled wheat changes who captures the processing margin along the chain.
Price and availability read-through
The practical consequence of a net downgrade is a tighter exportable surplus across the Black Sea and Caspian region than earlier forecasts assumed. Tighter availability from the cheapest origins tends to support export quotations and to narrow the discount that price-sensitive importers have relied on. It also raises the value of flexibility: buyers able to switch origin, port and loading window are better placed than those locked into a single supply line.
For producers and traders inside Kazakhstan, the upgraded outlook is an opening, but one capped by logistics rather than by the harvest. Rail car availability, border crossing throughput and transit arrangements determine how much of the theoretical surplus actually reaches paying customers within the marketing year.
What market participants are watching
- Whether subsequent FAO updates confirm the direction of the Russian and Ukrainian revisions or move them again.
- How much of Kazakhstan's additional supply travels as unmilled wheat versus wheat flour.
- Rail and transit capacity on the corridors out of Central Asia, which caps realisable export volume.
- The pace of large import tenders, which sets the tone for Black Sea and Caspian offers.
- Whether importers in Central Asia absorb the extra Kazakh wheat before it is offered further afield.
FAO publishes its cereal assessments on a rolling basis, and export projections are revised as harvest results, domestic consumption and shipment data accumulate. For now, the direction indicated by the latest outlook is a regional export pool that is smaller than previously expected, with Kazakhstan taking a larger share of a reduced total.