Uncapped raw-sugar import registration supports a stable Iran price outlook
Iran has opened raw-sugar import registration without a trader-history ceiling from 31 Shahrivar. The additional supply channel supports an outlook of stable or only moderately higher sugar prices from 4 to 10 Mehr, although the effect depends on import execution and refining availability.
Current prices show no sign of an immediate surge
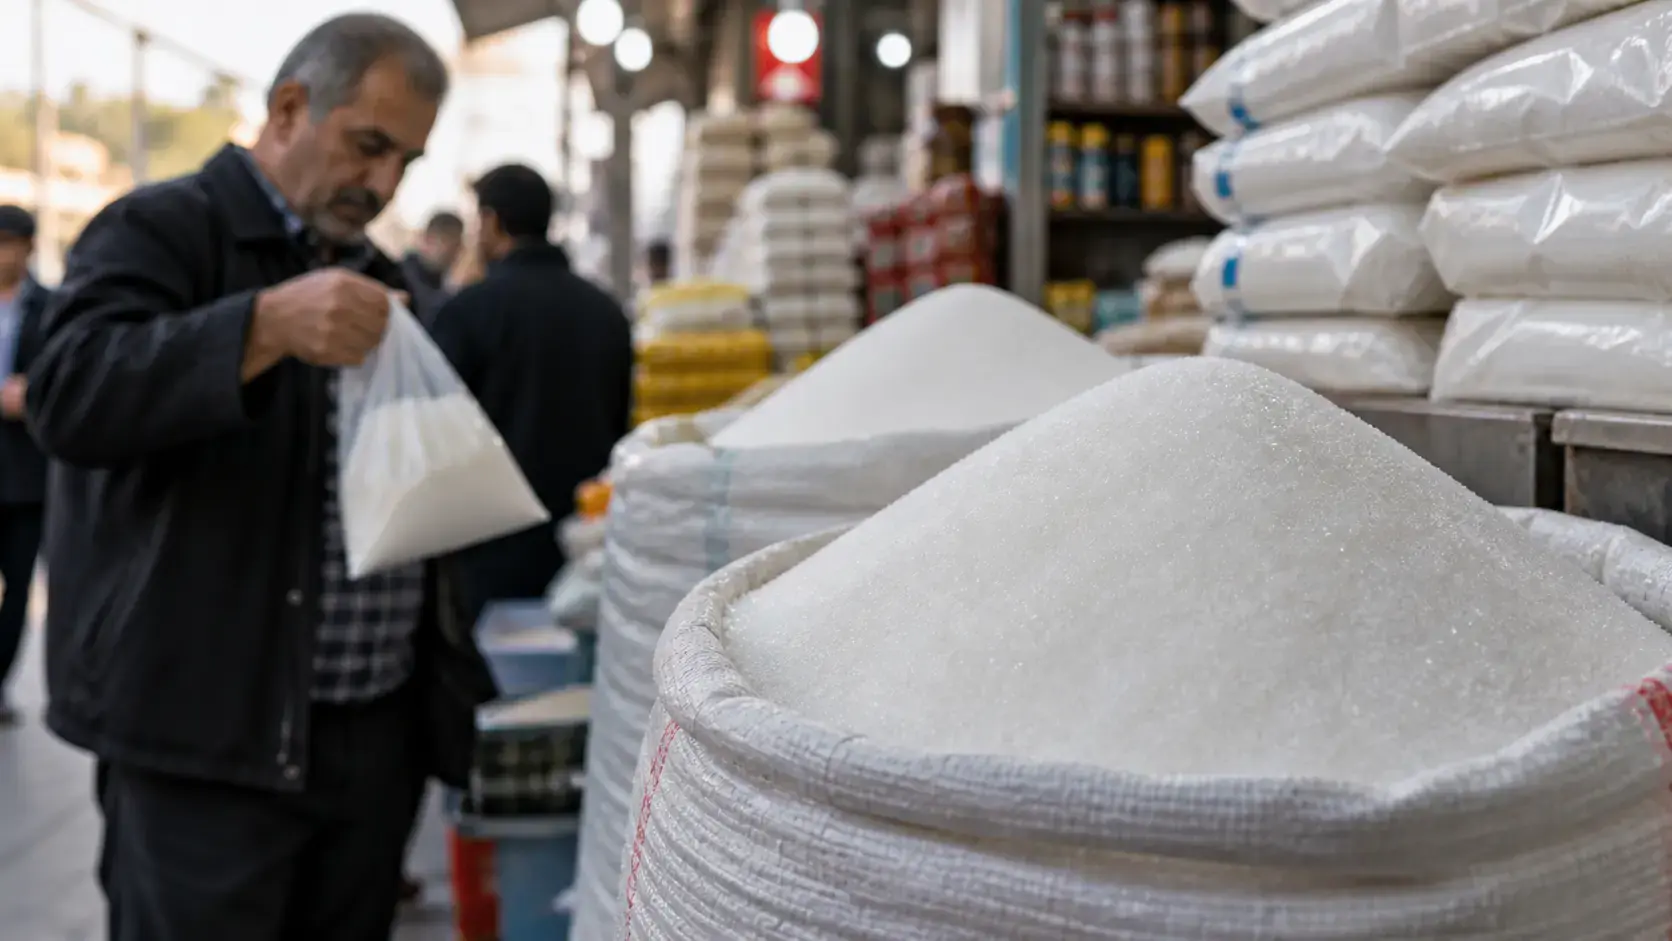
Iran’s sugar market entered the beginning of Mehr without indications of a sharp, one-off price increase. Packaged white sugar for consumers was quoted at 125,000 tomans, while bulk sugar stood at 108,500 tomans. The ex-factory sugar price was 93,500 tomans. Base prices for sugar cubes ranged from 115,000 to 151,000 tomans depending on quality.
The difference between the ex-factory and packaged quotations reflects the additional costs and margins accumulated through packaging and distribution. However, the source material does not identify a significant recent change in either the packaged or bulk benchmark. That relative stability provides the basis for expectations that the market will begin the coming week with limited movement rather than a sudden jump.
Import registration expands the potential supply pipeline
The main new development is the opening of raw-sugar import registration from 31 Shahrivar without the previous ceiling linked to a trader’s import history. Removing that restriction potentially allows a broader or larger volume of orders to enter the registration process. For importers, the measure creates room to secure raw material; for refiners, it may improve the prospective feedstock pipeline; and for distributors, it reduces the immediate case for pricing in an acute shortage.
Registration does not mean that raw sugar is already available in the domestic market. Orders must still translate into purchases, transport, customs clearance and refining before they can affect supplies of white sugar and sugar cubes. The timing of those stages will determine whether the policy influences physical availability in the week under review or mainly shapes expectations for later deliveries.
Stability remains the base case for 4-10 Mehr
For the period from Saturday 4 Mehr to Friday 10 Mehr, the central scenario is price stability or a limited increase. A more pronounced rise would require a stronger impulse from procurement costs, freight, foreign exchange or a disruption to supply. Conversely, successful import ordering could reinforce the supply side and make it harder for sellers to sustain abrupt price increases.
Market participants will therefore need to distinguish between registered demand for imports and cargoes that have become operationally available. Refiners will watch the cost and arrival schedule of raw sugar, while wholesalers and food manufacturers will compare those signals with the 93,500-toman factory quotation and the 108,500-toman bulk price. For consumers, the 125,000-toman packaged rate remains the visible benchmark. In the near term, the uncapped registration measure is more likely to moderate expectations than to produce an immediate fall in retail prices.