Hedge Funds Build 177 Million Barrel Net Long in US Gasoline and Diesel
Money managers held a net long position of about 177 million barrels in the main gasoline and diesel contracts as of September 1, while staying slightly bearish on crude oil, according to Petrochemiha. US diesel has moved above $5.90 a gallon and gasoline above $4.15, with gasoline stocks at a critical level. Record diesel crack spreads and an approaching refinery maintenance season point to refining capacity, not crude supply, as the binding constraint.
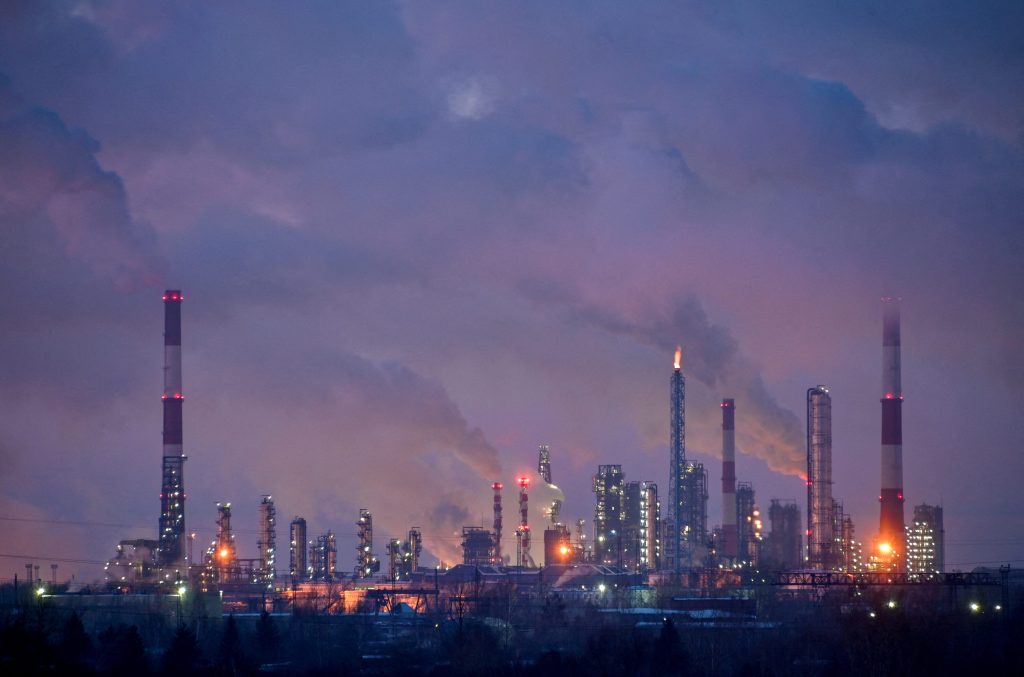
Hedge funds had accumulated a net long position of roughly 177 million barrels in the principal gasoline and diesel futures contracts by September 1, while their crude oil positioning remained slightly bearish, according to the industry publication Petrochemiha. The divergence between the two books marks a shift in where the market sees the binding constraint: not in the availability of crude, but in the capacity to convert it into finished fuel.
US product prices reflect the same pressure. Diesel has moved above $5.90 a gallon and gasoline above $4.15 a gallon, Petrochemiha reported, with gasoline inventories at what the publication described as a critical level. High export volumes and a shift in refinery yields toward diesel and jet fuel have held back gasoline output.
Positioning splits away from crude
A net long of 177 million barrels in refined products alongside a bearish crude book is a directional bet on refining margins rather than on the oil price itself. In a market where physical inventories are already thin, additional financial demand for product contracts can make price moves faster and sharper, amplifying volatility that originates in the physical system.
Petrochemiha links the change in fund positioning to changed expectations. A prolonged conflict has moved the market's working assumption from a temporary supply disruption toward a durable risk of shortage. Disrupted crude and product exports from the Middle East and Russia have reduced the flexibility of the global system, leaving fewer alternative barrels available to cover a regional outage. The publication also notes that the significance of the Strait of Hormuz is no longer limited to the volume of crude passing through it, since any disruption to the regional production, refining and export chain can reach markets as far away as the United States and Europe.
The bottleneck has moved downstream
The clearest indicator of the shift is the diesel crack spread, the difference between the price of crude entering a refinery and the value of the product it yields. Very high readings for diesel cracks in both the United States and Europe show that buyers are willing to pay far more for the fuel than the crude behind it is worth, a pattern that signals a shortage of refining capacity or product supply rather than an absolute shortage of crude.
Refiners have redirected part of their capacity toward diesel and jet fuel in recent months to meet demand for those grades, cutting the relative share of gasoline in the barrel and putting gasoline stocks under pressure. That creates a hard limit: even if more crude becomes available, gasoline or diesel supply can only rise quickly where there is spare refining capacity, suitable feedstock and operating time.
The United States now runs fewer refineries than it did several decades ago. That capacity may be sufficient under normal conditions, but during a large regional disruption the margin of spare capacity available for a fast response is limited.
Maintenance season meets low inventories
Seasonal turnarounds in the United States and other regions are arriving at a sensitive moment. Simultaneous reductions in operating capacity at several plants do not mean full shutdowns, but they lower aggregate output for several weeks at a point when inventories are already low. The result is an unfavourable combination of low stocks, constrained refining capacity, export disruption, seasonal demand and limited time to rebuild reserves.
A rise in diesel prices carries wider economic consequences than a comparable move in gasoline, since diesel feeds directly into road transport, shipping, industrial machinery, mining, agriculture and part of power generation. Sustained strength therefore transmits into freight costs and, subsequently, into inflationary pressure across other sectors.
Indicators to track
Petrochemiha argues that crude prices alone are no longer an adequate gauge of the market and lists the variables that should be followed in parallel:
- US and European gasoline and diesel inventories
- Crack spreads on diesel and other middle distillates
- Refinery utilisation rates
- Refinery maintenance schedules
- Product exports and imports
- The cost of and access to marine transport
- Regional product price differentials
On that reading, crude oil moving toward $100 a barrel is only part of the story. The larger risk is a very tight market for refined products, in which even higher crude supply may not close the gap in diesel, gasoline and jet fuel at the required speed. If supply disruptions persist and turnarounds begin as scheduled, diesel and other middle distillates are likely to remain the main pressure point in energy markets in the coming months.