Grain markets lack clear direction as oil, dollar and Black Sea risks compete
Cereal markets remain hesitant as higher oil prices, a stronger dollar and disrupted Black Sea shipping outweigh limited changes in physical supply. French wheat is gaining support, while low river levels are constraining European oilseed processing and feed markets.
Macroeconomic signals dominate physical fundamentals
Global cereal markets are struggling to establish a clear direction as macroeconomic developments overshadow relatively limited changes in physical supply. La France Agricole reports that Brent crude has risen 60% since the start of the year, reviving inflation concerns and influencing commodity markets, while conditions on the ground have changed little in the Black Sea region or the Middle East.
The dollar has strengthened as investors seek safety amid political and budget uncertainty in Europe, particularly France. The euro-dollar rate has fallen to its lowest level since May 2025, at 1.123, improving the competitiveness of French grain. The same currency move is working against US wheat exports and making European imports more expensive.
Black Sea disruption supports French wheat and barley
Attacks on commercial vessels near Bulgarian ports and the continued blockage of maritime exports are maintaining a risk premium and redirecting international grain flows. Import demand is gradually benefiting French wheat after September 2026 shipments fell short of expectations. October’s loading schedule is well filled, but November will be decisive before Southern Hemisphere supplies arrive. Argentine wheat is becoming more competitive and could capture business from France.
Saudi Arabia recently held a tender, while Egypt may return to the market. Algeria could also resume purchases, although it continues to exclude French wheat. Delivered Rouen wheat stands at €243.5 per tonne after reaching a season high of €250. In Chicago, December 2026 US wheat is struggling to hold $6.84 per bushel. Barley is trading near €222 per tonne in Rouen, compared with a season high of €226, as dwindling Romanian and Bulgarian supplies encourage buyers to consider Western European origins.
River logistics tighten European oilseed markets
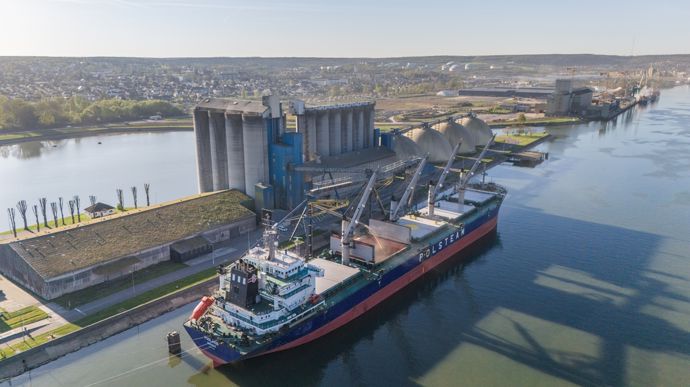
European feed manufacturers are buying more grain within the bloc because corn remains expensive. At the same time, dry planting conditions are affecting European barley, while the start of Ukraine’s harvest is increasing concern about winter storage capacity. Low water levels on the Rhine, Moselle and Danube are preventing normal river transport and have slowed crushing operations, including at the Mannheim site in Germany.
La France Agricole reports that FOB Moselle rapeseed fell by €25 per tonne to €51.5 per tonne in one week as crushing-site closures weakened immediate demand. Longer-term European supply remains tight: Argus expects Canada to provide only 1.5 million tonnes, while Australia could supply nearly 2.5 million tonnes, with the first vessels unlikely before January. Soybean meal at Montoir has risen to €455 per tonne, its highest since June 2024, while Chicago December 2026 meal exceeds $360 per short ton. US soybean production is projected above 121 million tonnes, and Brazil’s 2026-2027 planting has reached 10% in Mato Grosso amid continued El Niño concerns.