German copper-semifinished output falls 0.3% in weak start to 2026
Germany processed about 376,000 tonnes of copper into semifinished products in the first quarter of 2026, down 0.3% year on year. Higher wire output offset only part of the declines in sheet, strip, foil, bar, profile, tube and powder production.
Semifinished production remains subdued
Germany's copper-processing industry made a weak start to 2026, with total production of semifinished copper products broadly stagnating in the first quarter. About 376,000 tonnes of copper were processed into wire, sheet, strip, foil, bar, profile, tube and powder, according to figures reported by bvse and attributed to the German Copper Association, the Federal Statistical Office and calculations by Oliver Eisenberg of the association.
Output was 0.3% below the corresponding quarter of 2025. The modest headline decline concealed a marked divergence between wire and almost every other product category, indicating that demand was concentrated rather than broadly based across Germany's industrial copper market.
Wire gains while rolled and extruded products decline
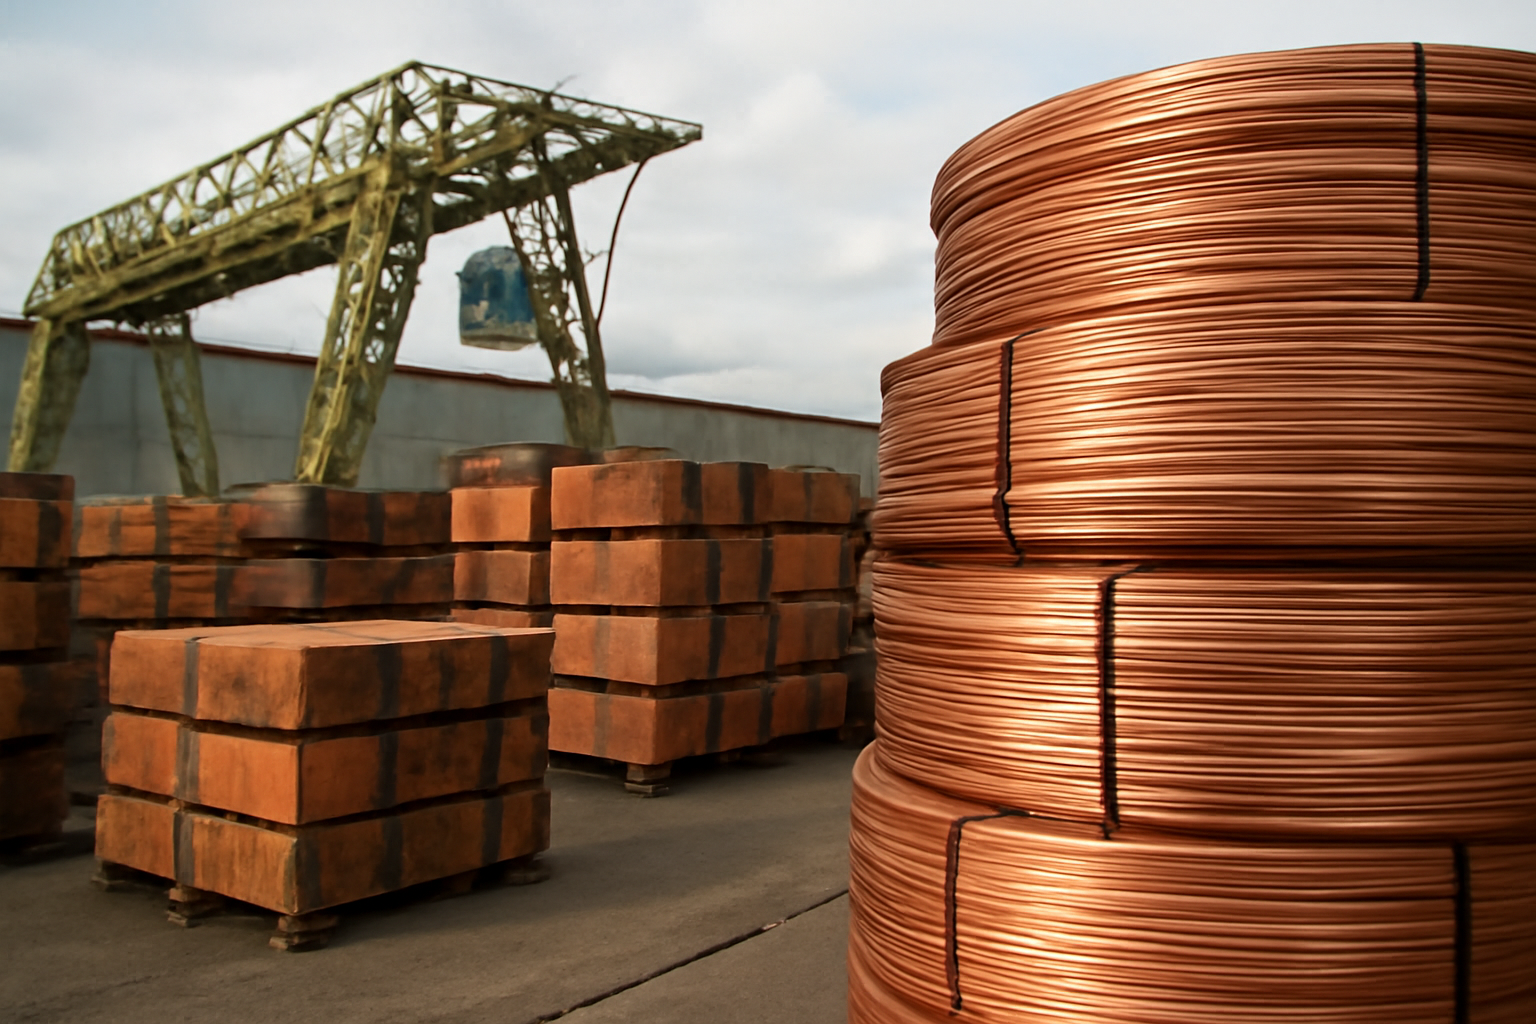
Copper wire, the largest segment by volume, was the only major area to record clear growth. Production increased 3.1% year on year to 192,000 tonnes. The category therefore represented more than half of all copper processed into semifinished products during the quarter.
The improvement in wire was insufficient to produce growth for the industry as a whole. Combined production of sheet, strip and foil together with bar and profile fell 3.9% from the first quarter of 2025 to 148,000 tonnes. These products form the second-largest block in the reported production mix, making their decline a substantial counterweight to the increase in wire.
Other categories also weakened. Copper-tube production declined by 1.7%, while copper-powder output fell by 2.7%. The source did not provide absolute tonnage for those two categories, but their contraction reinforces the picture of weakness across most of the industry's product portfolio.
Industrial demand and investment conditions in focus
The figures reflect the continuing weakness of Germany's industrial economy, which has weighed on copper processors. They provide no evidence yet of a sustained recovery: total output remains at a low level even though the wire segment expanded. Performance during the rest of 2026 will depend partly on whether any improvement in wider industrial activity reaches manufacturers of copper semifinished products.
This near-term weakness contrasts with copper's growing strategic role. The metal is required in large volumes for power-grid expansion, renewable energy, electric mobility and digital applications. Continued electrification is therefore expected to support longer-term demand, but the first-quarter data show that this prospective growth has not yet translated into a broad increase in German processing volumes.
The German Copper Association argues that policymakers must improve conditions for the domestic industry as decisions are made about how much copper processing will remain in Germany and Europe. It identifies affordable energy, predictable regulation and an industrial-policy environment that supports domestic value creation as important factors in company investment decisions. For producers and their customers, the immediate signal is mixed: wire demand is comparatively resilient, but weakness in rolled, extruded, tubular and powder products continues to restrain the overall market.