FAO Sugar Price Index Jumps 11.9% in August as Brazilian Output Falls and India Opens an Import Quota
The FAO Sugar Price Index averaged 106.4 points in August, 11.3 points above July and 11.9% higher month on month, the highest reading since June 2025. The FAO linked the move to lower European beet yields, El Nino risks in Asia, reduced Brazilian sugar output and India's duty-free raw sugar import quota. Conab projects a larger Brazilian cane crop but 2.9% less sugar, with ethanol taking the difference.
The FAO Sugar Price Index averaged 106.4 points in August, 11.3 points above the July reading and 11.9% higher month on month, the highest level since June 2025. The figures were reported by NewsDigitales, drawing on the Food and Agriculture Organization's monthly price series.
The move stood out even in a month when food commodities generally rose. The FAO Food Price Index reached 133.3 points, 1.9% above July, meaning sugar advanced far faster than cereals, vegetable oils, meat and dairy. The FAO attributed the jump to four factors:
- lower sugar beet yields in the European Union;
- weather risks linked to El Nino in Asian producing countries;
- reduced sugar output in Brazil;
- India's decision to open the door to duty-free raw sugar imports.
Brazil: more cane, less sugar
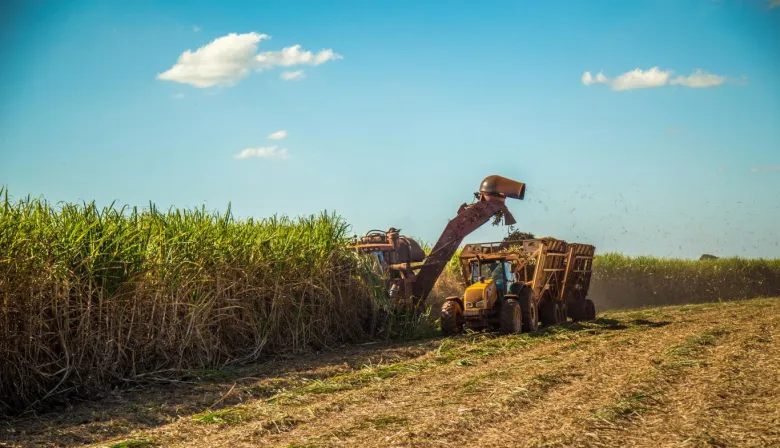
Brazilian supply numbers explain much of the tightness. Conab, the national crop agency, projects 705.2 million tonnes of sugarcane in 2026/27, 4.7% more than the previous season. Sugar production, however, is forecast at 42.89 million tonnes, 2.9% below the prior campaign.
Fuel accounts for the gap. Conab expects cane ethanol output to rise 9.7% to 29.98 billion litres, an additional incentive to direct raw material toward the fuel rather than the sweetener. The result is a projection that combines a larger cane crop with a smaller sugar supply, an outcome that holds only as long as the sugar-ethanol price parity favours distilling through the crushing season.
India adds a buyer to the market
India increased pressure from the demand side. The government authorised duty-free imports of raw sugar under a quota of 10 lakh metric tonnes, equivalent to one million tonnes, and advanced allocation rules during August and September, according to NewsDigitales.
The distinction matters for traders. Opening the quota shifts expectations and international quotations, but it does not mean the full volume has been bought or landed. Physical flows will depend on how allocations are distributed and on the arbitrage between world raw sugar values and Indian domestic prices. A duty-free quota in one of the main producing countries also removes a potential source of exportable supply at the same time as it adds a buyer.
Beet yields and El Nino
The weather component widens the uncertainty over the 2026/27 season. The FAO said heat and dryness forced downward revisions to sugar beet yield forecasts in the European Union, while conditions associated with El Nino are weighing on prospects among Asian producers. Both regions feed the same balance sheet: weaker European beet output tends to pull additional refined sugar demand into the world market, while Asian weather risk affects cane availability in the region that includes India and its neighbours.
What the index measures, and what it does not
The FAO series tracks international commodity quotations. It is not a retail price and does not transfer automatically to supermarket shelves, a point NewsDigitales emphasised in the Argentine context, where the index should not be confused with the shelf price of a packet of sugar. Any pass-through to consumers depends on local currency, taxes, distribution costs and domestic policy.
Two upcoming data points will frame the next stage. The FAO publishes its next monthly index on 2 October, while Argentina's statistics agency INDEC releases August consumer price data on 10 September. Until those figures and sugar-specific retail prices are available, the confirmed development is the deterioration in world supply expectations, expressed in a single-month gain of 11.9%.