Coface: Copper, Nickel and Aluminium Face Structural Deficits by 2035
A new Coface analysis reported by Il Sole 24 Ore projects structural supply deficits in copper, nickel and aluminium by 2035 as electrification outpaces mining and smelting capacity. Copper could face a shortfall of 1.5 to 6.5 million tonnes and refined nickel around 6.5 million tonnes under a Net Zero scenario, with copper and nickel prices seen nearly doubling over the decade.
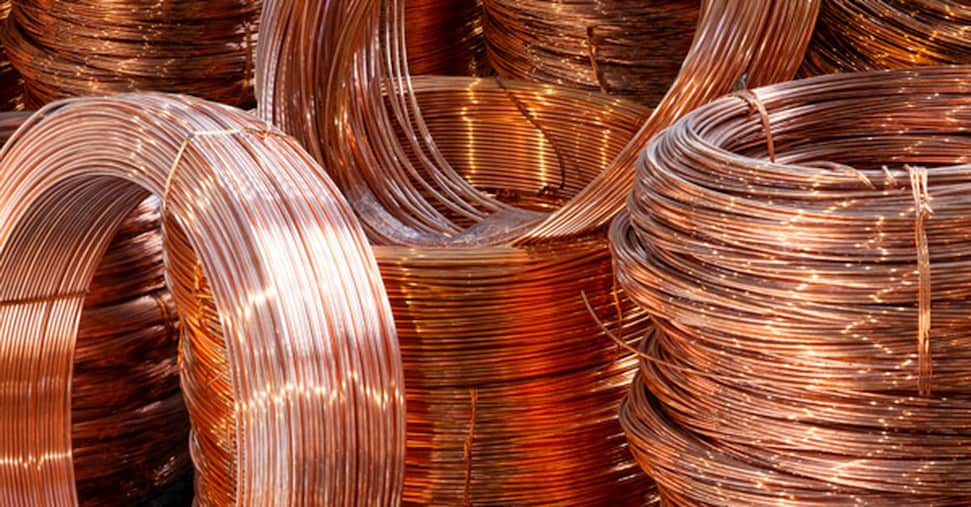
Copper, nickel and aluminium are heading for structural supply deficits by 2035, as electrification drives demand faster than constrained mining and processing capacity can respond, according to a new analysis by trade credit insurer Coface reported by Il Sole 24 Ore. The study points to a decade of sustained upward pressure on prices and argues that continuity of supply, rather than price alone, is becoming the primary risk for industrial buyers.
Demand is building on an already tight base
Metals consumption was rising well before low-emission technologies reached scale. Urbanisation, infrastructure spending and growth in emerging economies will continue to support global consumption in the coming years. Construction alone absorbs almost 50% of world steel consumption, while electrification already accounts for nearly three quarters of global copper demand. On top of that baseline comes demand tied to the energy transition and digitalisation: renewables, electric vehicles, batteries, power grids and data centres are all metal-intensive. Under the International Energy Agency's Announced Pledges Scenario, clean technologies could account for 35% of global copper and nickel demand by 2035.
Supply is slower and more concentrated
Fewer than 1% of mineral exploration projects ever reach actual production, and expanding capacity at existing projects now takes an average of close to 20 years, against less than 15 years at the start of the 2000s. Weaker returns on investment, the gradual decline in ore grades and rising costs are all holding back output growth.
Supply chains are also heavily concentrated. Indonesia produces 67% of the world's nickel ore, while China accounts for more than half of global refining capacity for several metals. Trade policy is tightening in parallel: at the end of 2025 there were 1,138 measures in force covering imports or exports of critical minerals, compared with just 357 ten years earlier.
Deficits metal by metal
- Copper, essential to electrification and digital infrastructure, could run a deficit of between 1.5 and 6.5 million tonnes by 2035 depending on the scenario. Under a Net Zero Emissions scenario the shortfall could reach 17% of world demand, with rapid data centre growth adding further pressure.
- Nickel is identified as the metal most exposed to the energy transition, largely because of its role in batteries and electric mobility. In a Net Zero scenario, the refined nickel market could show a deficit of about 6.5 million tonnes by 2035, close to 35% of projected demand.
- Aluminium faces a gap of 5 to 15 million tonnes, roughly 10% of projected demand. Here the binding constraint is not resource availability but industrial capacity, the investment needed to expand it and access to competitively priced electricity.
Price outlook and the corporate response
Coface expects these imbalances to keep pressure on prices through the next decade. Its forecasts see copper and nickel nearly doubling, with aluminium also posting a significant increase. Steel and zinc look less vulnerable, thanks to less rigid supply conditions and lower exposure to the new demand created by the energy transition.
«The energy transition is making access to critical metals an increasingly strategic issue for companies. Growth in demand for copper, nickel and aluminium is running into supply with little flexibility, very long timelines for developing new production capacity and supply chains heavily concentrated in a few countries», said Ernesto De Martinis, chief executive of Coface Mediterranean & Africa Region. He added that the risk for companies concerns not only possible price increases but also security of supply and the ability to keep production processes competitive, and that diversifying sources, investing in recycling and cutting dependence on the most critical raw materials will matter more for supply chain resilience.